How to Build Wealth on an Average Salary: A Practical Guide to Financial Freedom
Building wealth is often associated with high-paying jobs, successful businesses, expensive investments, or inherited money. Many people believe that becoming financially successful requires earning a six-figure salary or having a large amount of money to invest. However, this belief overlooks one important fact: building wealth is not just about how much money you earn; it is also about how effectively you manage, save, invest, and grow it.
If you earn an average salary, you can still build a financially secure future. Whether you are a salaried employee, a young professional, a government worker, or someone managing household expenses on a limited income, the right financial habits can help you gradually accumulate wealth.
In India, many middle-income households face similar financial challenges. Monthly salaries must cover rent, groceries, electricity bills, transportation, children’s education, healthcare, loan repayments, and other essential expenses. After managing these responsibilities, investing may seem difficult. Some people save whatever remains at the end of the month, while others postpone investing because they believe their income is too small.
The problem is that waiting for a higher salary before starting your financial journey can cost you valuable time.
The good news is that you do not need to become rich before you start building wealth. You need a realistic financial plan, consistent savings, suitable investments, controlled expenses, and patience.
This guide explains how to build wealth on an average salary, even when your monthly income is limited. It covers practical budgeting strategies, investment options, debt management, emergency funds, long-term financial planning, and common mistakes to avoid.
By the end of this article, you will understand how to make your salary work harder, develop sustainable financial habits, and gradually move towards financial independence.
1. Understanding What It Means to Build Wealth on an Average Salary (How to Build Wealth on an Average Salary)
Before discussing investment strategies, it is essential to understand what wealth actually means.
Wealth is not simply the amount of money you earn every month. A person earning ₹1 lakh per month may have very little wealth if most of their income goes towards expenses and debt repayments.
On the other hand, someone earning ₹35,000 per month may gradually accumulate meaningful wealth through disciplined saving, investing, and responsible financial decisions.
What Is Wealth?
Wealth refers to the financial resources and assets you own after accounting for your liabilities.
These resources may include:
- Money in savings accounts.
- Fixed deposits and recurring deposits.
- Equity mutual funds and stocks.
- Public Provident Fund (PPF) investments.
- Employees’ Provident Fund (EPF) savings.
- National Pension System (NPS) investments.
- Gold and other eligible investments.
- Residential or commercial property.
- Other income-generating assets.
Your actual financial position can be measured through your net worth.
Net Worth = Total Assets − Total Liabilities
For example, imagine someone has:
| Financial asset or liability | Amount |
|---|---|
| Savings account | ₹80,000 |
| Mutual fund investments | ₹2,00,000 |
| EPF balance | ₹1,50,000 |
| Gold | ₹70,000 |
| Personal loan | ₹1,00,000 |
| Credit card outstanding | ₹20,000 |
Total assets equal ₹5,00,000, while total liabilities equal ₹1,20,000.
Therefore:
Net worth = ₹5,00,000 − ₹1,20,000 = ₹3,80,000.
Tracking net worth helps you understand whether your financial situation is improving over time.
Why Your Salary Does Not Determine Your Financial Future
A higher salary provides more opportunities to save and invest, but it does not automatically create wealth.
Consider two individuals:
Person A:
- Monthly salary: ₹80,000
- Monthly expenses: ₹75,000
- Monthly savings: ₹5,000
Person B:
- Monthly salary: ₹40,000
- Monthly expenses: ₹30,000
- Monthly savings: ₹10,000
Person B earns half as much as Person A but saves twice as much every month.
This example demonstrates why financial discipline matters.
Of course, living expenses differ based on family size, location, responsibilities, and lifestyle. Someone living in Mumbai may face different financial pressures from someone living in a smaller city.
The objective is not to compare your salary with someone else’s. It is to create a financial system that works within your circumstances.
2. Set Clear Financial Goals Before You Start Investing
One of the biggest mistakes people make is investing without knowing why they are investing.
Buying mutual funds, opening fixed deposits, or purchasing gold without a financial objective can lead to unplanned decisions.
Before investing, identify what you want your money to achieve.
Short-Term Financial Goals
Short-term goals generally involve expenses you expect to meet within the next one to three years.
Examples include:
- Purchasing a laptop or smartphone.
- Planning a family vacation.
- Saving for a two-wheeler.
- Paying for a professional course.
- Building an emergency fund.
- Saving for a wedding.
For these goals, capital protection and accessibility are generally more important than chasing high investment returns.
Suitable options may include savings accounts, recurring deposits, and appropriate short-term deposit products.
Medium-Term Financial Goals
Medium-term goals generally fall within a three-to-seven-year period.
Examples include:
- Saving for a home down payment.
- Purchasing a car.
- Funding higher education.
- Starting a small business.
- Planning a major family expense.
The appropriate investment approach depends on your timeline and ability to tolerate losses.
You may consider a combination of relatively stable investments and carefully selected market-linked investments, depending on when you need the money.
Long-Term Financial Goals
Long-term goals usually require more than seven years.
Examples include:
- Retirement planning.
- Building long-term financial security.
- Children’s higher education.
- Creating wealth for future generations.
- Achieving financial independence.
Long-term goals provide more time for investments to potentially benefit from compounding.
Equity mutual funds, diversified investments, EPF, PPF, and NPS may play different roles depending on your financial situation and eligibility.
Make Your Goals Specific
Instead of saying, “I want to become rich,” define your goals clearly.
For example:
| Financial goal | Target amount | Time period |
|---|---|---|
| Emergency fund | ₹1,50,000 | 2 years |
| Home down payment | ₹5,00,000 | 6 years |
| Retirement investment | ₹50 lakh | 25 years |
| Skill development | ₹40,000 | 1 year |
These are illustrative targets, not universal recommendations.
Once your goals are defined, you can calculate how much you need to save and invest every month.
3. Understand Your Monthly Income and Expenses
You cannot build wealth consistently without understanding where your money goes.
Many salaried individuals know their monthly salary but cannot identify how much they spend on food delivery, online shopping, subscriptions, transportation, and other small purchases.
These expenses may appear insignificant individually, but together they can reduce your savings considerably.
Track Every Expense
Start by tracking your expenses for at least 30 days.
Divide your spending into categories:
Fixed expenses:
- House rent or home loan EMI.
- Electricity and water bills.
- Internet and mobile bills.
- Insurance premiums.
- School fees.
- Existing loan repayments.
Variable expenses:
- Groceries.
- Fuel and transportation.
- Restaurant visits.
- Shopping.
- Entertainment.
- Personal care.
Occasional expenses:
- Medical expenses.
- Festival celebrations.
- Vehicle maintenance.
- Annual subscriptions.
- Home repairs.
- Travel.
You can use a spreadsheet, budgeting application, or simple notebook.
The objective is to identify spending patterns rather than eliminate every enjoyable activity.
Calculate Your Savings Rate
Your savings rate tells you what percentage of your income you save.
Formula:
Savings Rate = (Monthly Savings ÷ Monthly Take-Home Income) × 100
For example:
- Monthly take-home salary: ₹40,000
- Monthly savings: ₹6,000
Savings rate = 15%.
This gives you a measurable starting point.
If you currently save only 5% of your income, you do not need to immediately increase it to 30%.
Start with a realistic amount and gradually improve your savings rate.
4. Follow a Practical Budgeting Strategy
A budget helps you distribute your salary according to your financial priorities.
One popular budgeting method is the 50/30/20 rule.
According to this method:
- 50% of income goes towards needs.
- 30% goes towards wants.
- 20% goes towards savings and investments.
For someone earning ₹40,000 per month, the allocation would look like this:
| Category | Percentage | Monthly amount |
|---|---|---|
| Essential expenses | 50% | ₹20,000 |
| Lifestyle expenses | 30% | ₹12,000 |
| Savings and investments | 20% | ₹8,000 |
| Total | 100% | ₹40,000 |
However, the 50/30/20 rule is a guideline, not a compulsory formula.
If you live in an expensive city or support your family financially, essential expenses may exceed 50%.
You can adjust the allocation to match your circumstances.
Try the 60/20/20 Budget
Another approach is:
- 60% for essential expenses.
- 20% for lifestyle spending.
- 20% for saving and investing.
For a ₹30,000 salary:
| Category | Amount |
|---|---|
| Essential expenses | ₹18,000 |
| Lifestyle expenses | ₹6,000 |
| Savings and investments | ₹6,000 |
This approach may be more realistic for some households.
Use Zero-Based Budgeting
Zero-based budgeting means assigning every rupee of your income a purpose.
For example, if you earn ₹35,000, distribute the entire amount among:
- Household expenses.
- Rent.
- Transportation.
- Savings.
- Investments.
- Insurance.
- Entertainment.
- Emergency fund contributions.
The objective is not to spend everything. Savings and investments are also assigned purposes.
This approach reduces unnecessary spending and helps you remain accountable.
5. Pay Yourself First: Save Before Spending
Many people follow this pattern:
- Receive salary.
- Pay bills.
- Purchase necessary items.
- Spend on entertainment.
- Save whatever remains.
Unfortunately, very little may remain at the end of the month.
A better approach is to pay yourself first.
This means transferring a predetermined amount into savings or investments immediately after receiving your salary.
How to Implement This Strategy
Suppose your monthly take-home salary is ₹35,000.
You decide to save ₹5,000 every month.
As soon as your salary arrives:
- Transfer ₹2,000 to your emergency fund.
- Invest ₹2,000 through a suitable monthly investment plan.
- Transfer ₹1,000 to a separate financial goal.
The remaining ₹30,000 becomes your spending budget.
You can automate recurring transfers and investment contributions to make this process easier.
Why Automation Works
Automation reduces the temptation to spend money before saving it.
It also helps maintain consistency during busy months.
However, keep enough money in your primary bank account to cover essential expenses and avoid failed automatic payments or overdraft charges.
6. Build an Emergency Fund Before Taking Investment Risks
An emergency fund is one of the most important parts of a wealth-building strategy.
Unexpected financial situations can occur at any time.
Examples include:
- Job loss.
- Medical emergencies.
- Unexpected home repairs.
- Vehicle breakdowns.
- Family emergencies.
- Temporary income interruption.
Without emergency savings, you may need to withdraw long-term investments or borrow money at high interest rates.
How Much Emergency Fund Do You Need?
A common starting guideline is to maintain three to six months of essential living expenses.
People with unstable income, dependants, or limited job security may need a larger reserve.
Suppose your monthly essential expenses are ₹20,000.
Your emergency fund target could be:
| Coverage period | Emergency fund |
|---|---|
| 3 months | ₹60,000 |
| 4 months | ₹80,000 |
| 6 months | ₹1,20,000 |
The correct amount depends on your responsibilities and employment situation.
Where Should You Keep Your Emergency Fund?
Emergency money should be accessible and relatively stable.
Possible options include:
- Savings bank account.
- Sweep-in fixed deposit.
- Short-term fixed deposit.
- Other suitable low-risk, liquid instruments.
Avoid keeping your entire emergency fund in equity mutual funds or stocks.
Market-linked investments can fall in value precisely when you need the money.
How to Build an Emergency Fund on a Small Salary
You do not need to save the entire amount immediately.
Suppose your target is ₹60,000.
If you save ₹2,000 every month, you will accumulate ₹24,000 in one year, excluding any interest.
Continue building the fund gradually while managing other financial priorities.
7. Start Investing Even If You Have Only ₹500 or ₹1,000
One of the most effective ways to build wealth on an average salary is to start investing regularly.
Many beginners believe that investing requires a large amount of money.
That is not necessarily true.
Several financial products allow small contributions, subject to their minimum investment requirements and eligibility conditions.
Why Starting Early Matters
Investing early provides more time for potential compounding.
Compounding occurs when investment returns generate additional returns over time.
For example, imagine you invest ₹2,000 every month for 20 years.
Your total contribution would be:
₹2,000 × 12 × 20 = ₹4,80,000.
If your investment earns an assumed annualized return of 10%, compounded monthly for illustration, the accumulated amount could be approximately ₹15.2 lakh.
This is only a mathematical illustration, not a guaranteed investment outcome.
Actual returns may be higher or lower, and market-linked investments can lose value.
Understand the Power of SIP
A Systematic Investment Plan (SIP) allows you to invest a fixed amount regularly in a mutual fund.
For example:
- Monthly SIP: ₹1,000.
- Investment frequency: Monthly.
- Investment period: 20 years.
- Total invested: ₹2,40,000.
If the investment earns an illustrative annualized return of 10%, the future value could be approximately ₹7.6 lakh.
The actual value will depend on market performance, expenses, taxes, and investment timing.
Why SIPs Are Useful for Salaried Employees
SIPs offer several practical advantages:
- Encourage disciplined investing.
- Allow regular small contributions.
- Reduce the need to time every market entry.
- Support long-term financial goals.
- Make it easier to invest after receiving a monthly salary.
However, SIPs do not eliminate market risk or guarantee profits.
You should select a mutual fund based on your investment horizon, risk tolerance, financial goals, and understanding of the product.
8. Understand Different Investment Options Available in India
Choosing suitable investments is essential when building wealth on an average salary.
Different investments have different risk levels, liquidity features, tax treatment, and expected return characteristics.
You should not invest simply because a particular product is popular.
Understand how each option works before committing your money.
8.1 Mutual Funds
Mutual funds collect money from multiple investors and invest it according to a defined investment objective.
Depending on the scheme, investments may be made in:
- Equity shares.
- Government securities.
- Corporate bonds.
- Money-market instruments.
- A combination of asset classes.
Types of mutual funds include:
Equity mutual funds
These funds primarily invest in shares.
They may be suitable for long-term financial goals if you can tolerate market fluctuations.
Examples include:
- Large-cap funds.
- Mid-cap funds.
- Small-cap funds.
- Flexi-cap funds.
- Index funds.
Debt mutual funds
These funds primarily invest in debt and money-market instruments.
Their risk depends on factors such as credit quality, interest-rate sensitivity, and portfolio composition.
They are not equivalent to guaranteed bank deposits.
Hybrid mutual funds
These funds invest in a combination of equity and debt instruments.
Their risk depends on the asset allocation and investment strategy.
Index funds
Index funds aim to replicate the performance of a particular market index, subject to tracking differences and expenses.
They can offer a relatively straightforward way to access diversified market exposure.
8.2 Public Provident Fund (PPF)
The Public Provident Fund is a government-backed small-savings scheme designed for long-term savings.
Important characteristics include:
- Long investment horizon.
- Government-backed structure.
- Defined contribution limits.
- Prescribed interest-rate revisions.
- Specific withdrawal and maturity rules.
- Tax benefits subject to applicable law.
PPF may be useful for people seeking a long-term savings option with relatively predictable rules.
However, it has a long lock-in period and is not appropriate for money you may need immediately.
Always check the latest contribution limits, interest rates, and tax provisions before investing.
8.3 Employees’ Provident Fund (EPF)
EPF is an important retirement savings arrangement for eligible salaried employees.
Both employee and employer contributions may form part of the retirement savings structure, according to applicable rules.
Benefits include:
- Regular retirement contributions.
- Long-term savings discipline.
- Interest credited according to applicable rules.
- Potential tax advantages, subject to conditions.
If you are employed in an organization covered by EPF provisions, review your salary structure and EPF statement periodically.
Do not ignore this balance while calculating your overall wealth.
8.4 National Pension System (NPS)
The National Pension System is a market-linked retirement savings scheme.
It provides exposure to different asset classes, depending on the selected investment approach.
Key features include:
- Retirement-focused savings.
- Multiple investment options.
- Equity and debt exposure.
- Regulated pension-fund management.
- Specific withdrawal and exit conditions.
NPS can be considered as part of retirement planning.
However, understand its withdrawal rules, tax treatment, charges, and restrictions before investing.
8.5 Fixed Deposits (FDs)
Fixed deposits allow you to deposit money with a bank or eligible financial institution for a predetermined period.
Their features generally include:
- Predetermined interest terms.
- Different tenure options.
- Flexible deposit amounts.
- Various payout choices.
- Relatively predictable maturity values, subject to issuer and applicable conditions.
Fixed deposits can be useful for short-term goals and conservative savings.
Compare interest rates, premature withdrawal conditions, tax implications, and applicable deposit insurance coverage.
8.6 Recurring Deposits (RDs)
A recurring deposit allows you to contribute a fixed amount regularly.
For example, you could deposit ₹1,500 every month for a selected tenure.
RDS can help beginners develop disciplined savings habits.
They may be suitable for planned expenses and people who prefer a structured savings arrangement.
8.7 Gold Investments
Gold can play a role in portfolio diversification, depending on your financial objectives.
Investment routes include:
- Gold ETFs.
- Eligible gold mutual funds.
- Sovereign Gold Bonds, where new issuance or secondary-market availability applies.
- Physical gold.
Each option has different costs, liquidity, risks, and tax treatment.
Physical jewellery should not automatically be treated as an efficient investment because making charges, resale deductions, and purity considerations can affect its value.
8.8 Direct Stocks
Buying individual company shares provides direct exposure to businesses.
However, stock investing requires research and an understanding of:
- Business performance.
- Revenue and profit trends.
- Debt levels.
- Management quality.
- Valuation.
- Industry risks.
- Competitive position.
Beginners should avoid buying shares based only on social media recommendations or short-term price movements.
If you do not have sufficient knowledge or time, diversified funds may be a more manageable starting point.
9. Create a Simple Investment Plan Based on Your Salary
You do not need a complicated investment portfolio to begin building wealth.
The right starting point is a plan that you can maintain consistently.
Consider the following examples.
Example 1: Monthly Salary of ₹20,000
A person earning ₹20,000 may have limited investment capacity.
An illustrative monthly allocation could be:
| Purpose | Amount |
|---|---|
| Essential expenses | ₹14,000 |
| Lifestyle expenses | ₹2,000 |
| Emergency savings | ₹2,000 |
| Long-term investment | ₹1,000 |
| Short-term savings | ₹1,000 |
| Total | ₹20,000 |
The priority should be building a basic emergency reserve and avoiding expensive debt.
Example 2: Monthly Salary of ₹30,000
| Purpose | Amount |
|---|---|
| Essential expenses | ₹18,000 |
| Lifestyle expenses | ₹5,000 |
| Emergency savings | ₹3,000 |
| Mutual fund SIP | ₹2,000 |
| Other savings | ₹2,000 |
| Total | ₹30,000 |
This allocation provides a balance between present expenses and future financial goals.
Example 3: Monthly Salary of ₹40,000
| Purpose | Amount |
|---|---|
| Essential expenses | ₹22,000 |
| Lifestyle expenses | ₹6,000 |
| Emergency fund | ₹4,000 |
| Mutual fund SIP | ₹4,000 |
| Other long-term savings | ₹2,000 |
| Other financial goals | ₹2,000 |
| Total | ₹40,000 |
The allocation should change once the emergency fund is complete.
You could then redirect some of the emergency savings contribution towards long-term investments or other goals.
Example 4: Monthly Salary of ₹50,000
| Purpose | Amount |
|---|---|
| Essential expenses | ₹25,000 |
| Lifestyle expenses | ₹8,000 |
| Emergency savings | ₹5,000 |
| Mutual fund investments | ₹7,000 |
| Retirement savings | ₹3,000 |
| Other goals | ₹2,000 |
| Total | ₹50,000 |
These examples are educational illustrations rather than prescribed financial plans.
Your actual budget should reflect rent, family responsibilities, existing debt, insurance needs, location, and financial priorities.
10. Increase Your Income Instead of Depending Only on Expense Reduction
Saving money is important, but there is a limit to how much you can reduce your expenses.
You cannot eliminate rent, food, healthcare, or every essential household expense.
Therefore, another important wealth-building strategy is increasing your earning potential.
Develop High-Value Skills
Investing in your skills can improve your career opportunities and future income.
Depending on your profession, useful skills may include:
- Digital marketing.
- Data analytics.
- Software testing.
- Programming.
- Financial analysis.
- Project management.
- Graphic design.
- Communication.
- Business development.
- Artificial intelligence tools.
Choose skills based on industry demand, your interests, and realistic employment opportunities.
A professional certification or online course can be useful, but only when it develops skills that employers or clients actually value.
Negotiate Your Salary
Many employees remain in the same salary range for years because they do not discuss compensation.
Before negotiating:
- Research salary ranges for similar roles.
- Identify your professional achievements.
- Prepare examples of measurable contributions.
- Understand your responsibilities.
- Present a reasonable salary expectation.
- Discuss opportunities for growth.
A well-planned job change can also improve your income, although job security, working conditions, benefits, and career development should be considered.
Start a Side Income
A side income can provide additional money for savings and investments.
Possible opportunities include:
- Freelancing.
- Online tutoring.
- Content writing.
- Website development.
- Graphic design.
- Consulting.
- Selling digital products.
- Part-time professional services.
- Small online businesses.
For example, if you earn an additional ₹5,000 per month and invest it regularly, you can significantly increase your total contributions over time.
However, do not sacrifice your health or primary employment responsibilities for an unsustainable side business.
Also consider applicable tax and legal obligations.
11. Avoid Lifestyle Inflation When Your Salary Increases
Lifestyle inflation happens when spending increases alongside income.
For example, imagine your salary increases from ₹30,000 to ₹40,000.
Instead of increasing savings, you may start spending more on:
- Expensive restaurants.
- Premium smartphones.
- New clothing.
- Bigger vehicles.
- Higher rent.
- Frequent vacations.
- Unnecessary subscriptions.
Your income increases, but your financial position may remain almost unchanged.
Follow the 50% Salary-Increment Rule
A useful personal budgeting guideline is to allocate at least half of every salary increase towards financial goals.
Suppose your monthly salary increases by ₹8,000.
You could distribute it as follows:
- ₹4,000 towards additional savings and investments.
- ₹2,000 towards improved lifestyle spending.
- ₹2,000 towards debt reduction or other financial goals.
This allows you to enjoy career growth without allowing every additional rupee to disappear into lifestyle expenses.
The percentage can be adjusted according to your circumstances.
12. Manage Debt Before It Becomes a Financial Burden
Debt can slow down wealth creation, especially when interest rates are high.
Not every loan is necessarily harmful. However, borrowing for unnecessary purchases or maintaining expensive credit card balances can damage your financial progress.
Understand Different Types of Debt
High-interest debt:
- Credit card revolving balances.
- Expensive personal loans.
- Certain short-term consumer loans.
These debts should generally receive priority because interest charges can accumulate quickly.
Purpose-based debt:
- Home loans.
- Education loans.
- Business loans.
- Vehicle loans.
These require individual assessment based on interest rates, repayment terms, cash flow, and financial objectives.
Use the Debt Avalanche Method
The debt avalanche method focuses on repaying the debt with the highest interest rate first.
Steps:
- List all outstanding debts.
- Write down their interest rates.
- Continue making minimum required payments on every debt.
- Direct additional repayment money towards the highest-interest debt.
- Once that debt is cleared, move to the next highest-interest debt.
This approach can reduce total interest costs compared with paying lower-interest debts first, assuming other terms remain comparable.
Consider the Debt Snowball Method
The debt snowball method focuses on clearing the smallest outstanding balance first.
It may provide psychological motivation because you can eliminate individual debts more quickly.
However, it may cost more in interest if higher-interest debts remain unpaid for longer.
Choose the method you can follow consistently.
Avoid Unnecessary EMI Commitments
Before purchasing something through EMI, ask yourself:
- Do I genuinely need this product?
- Can I afford the EMI comfortably?
- Are there processing fees?
- What is the effective interest rate?
- Will this EMI interfere with my savings?
- Am I purchasing it because of an advertisement or social pressure?
A product that appears affordable through a small monthly payment may become expensive over the full repayment period.
13. Protect Your Wealth With Proper Insurance
Building wealth is not only about accumulating assets. It is also about protecting yourself and your family against major financial risks.
One unexpected medical emergency or income disruption can affect years of savings.
Health Insurance
Healthcare expenses can create significant financial pressure.
A suitable health insurance policy can help cover eligible medical expenses according to its terms and conditions.
Before selecting a policy, compare:
- Sum insured.
- Hospital network.
- Waiting periods.
- Room-rent restrictions.
- Exclusions.
- Co-payment requirements.
- Restoration benefits.
- Claim procedures.
- Premium affordability.
Do not choose a policy based only on its lowest premium.
Term Life Insurance
If your family depends on your income, term life insurance may be an important part of financial protection.
It provides financial protection to eligible beneficiaries if the insured person dies during the policy term, subject to policy conditions.
The required cover depends on:
- Family expenses.
- Outstanding loans.
- Number of dependants.
- Children’s education requirements.
- Existing assets.
- Future financial obligations.
Term insurance is different from investment-linked life insurance products.
Evaluate protection needs separately from investment needs.
Personal Accident and Disability Coverage
A serious accident can affect your ability to earn.
Depending on your occupation and financial responsibilities, personal accident or disability coverage may be worth considering.
The goal is to prevent an unexpected event from forcing your family to liquidate long-term investments.
14. Understand the Importance of Compound Growth
Compounding is one of the most important concepts in long-term investing.
It occurs when returns generated by an investment are reinvested and subsequently generate additional returns.
Over a sufficiently long period, the growth can become increasingly significant.
Example: Investing ₹2,000 Every Month
Suppose you invest ₹2,000 per month.
Your contributions would be:
| Investment period | Total contribution |
|---|---|
| 5 years | ₹1,20,000 |
| 10 years | ₹2,40,000 |
| 15 years | ₹3,60,000 |
| 20 years | ₹4,80,000 |
| 25 years | ₹6,00,000 |
Now consider an illustrative annualized return assumption of 10%.
Using monthly contributions and monthly compounding, the approximate future values would be:
| Investment period | Approximate value |
|---|---|
| 5 years | ₹1.55 lakh |
| 10 years | ₹4.10 lakh |
| 15 years | ₹8.29 lakh |
| 20 years | ₹15.19 lakh |
| 25 years | ₹26.52 lakh |
These amounts are illustrative estimates, not guaranteed returns.
Actual equity investment outcomes may differ significantly.
Why Time Matters More Than You Think
Consider two investors.
Investor A starts investing ₹2,000 per month at age 25 and continues for 20 years.
Investor B starts investing ₹2,000 per month at age 35 and continues for 20 years.
Investor A finishes investing at age 45, while Investor B finishes at age 55.
Even though both invest the same monthly amount for the same number of years, Investor A has an additional decade for the accumulated investment to remain invested and potentially grow.
This illustrates why delaying investments can affect long-term financial outcomes.
15. Increase Your SIP Amount as Your Salary Grows
Starting with a small SIP is perfectly reasonable.
However, if your income increases, consider increasing your investment contribution.
This is commonly called a step-up SIP.
Example of Annual SIP Increases
Suppose you start with a monthly SIP of ₹2,000 and increase it by 10% every year.
Your monthly contribution would gradually become:
| Year | Monthly SIP |
|---|---|
| Year 1 | ₹2,000 |
| Year 2 | ₹2,200 |
| Year 3 | ₹2,420 |
| Year 4 | ₹2,662 |
| Year 5 | ₹2,928 |
Over time, this approach can substantially increase the amount you invest.
You do not need to increase your SIP by exactly 10%.
Even a smaller increase can be useful if it fits your financial situation.
Why Step-Up Investing Works
It connects your investment plan with your income growth.
Instead of keeping investments unchanged for decades, you gradually increase contributions as your earning capacity improves.
This can help you work towards larger financial goals without making a dramatic lifestyle adjustment.
16. Understand Inflation and Its Impact on Your Wealth
Inflation refers to the general increase in prices over time.
It reduces the purchasing power of money.
For example, imagine that a household spends ₹20,000 per month today on a particular set of expenses.
If prices increase by an illustrative 6% annually, the same expenses could cost approximately ₹35,800 per month after ten years.
This is why simply keeping all your money in a savings account may not be sufficient for long-term wealth creation.
Why Inflation Matters for Financial Planning
Inflation affects:
- Food expenses.
- Healthcare costs.
- Education fees.
- Housing.
- Transportation.
- Retirement requirements.
- Household maintenance.
Your financial goals should consider the future cost of living rather than only today’s prices.
How to Protect Your Purchasing Power
Depending on your financial goals and risk tolerance, you may consider a diversified combination of:
- Equity investments.
- Fixed-income instruments.
- Retirement savings.
- Inflation-conscious financial planning.
- Suitable real assets.
No investment guarantees that it will consistently outperform inflation.
Review your investment allocation periodically instead of assuming that one product will solve every financial problem.
17. Create Multiple Sources of Income
Depending entirely on one salary can make your financial situation vulnerable.
If your job ends or your employer reduces your income, your entire financial plan may be affected.
Building additional income sources can improve financial flexibility.
Active Income
Active income requires your time or direct effort.
Examples include:
- Salary.
- Freelancing.
- Consulting.
- Tuition classes.
- Part-time employment.
- Business services.
Passive or Investment-Related Income
Some assets may generate income without requiring the same level of daily involvement.
Examples include:
- Interest from eligible deposits.
- Dividends from shares or funds.
- Rental income.
- Certain business ownership arrangements.
However, passive income is rarely completely effortless.
Rental properties require maintenance, dividend payments are not guaranteed, and business investments involve risks.
Build One Additional Income Stream First
You do not need to create five income sources immediately.
Start with one realistic opportunity.
For example:
A salaried employee with writing skills may begin freelance content writing.
A software professional may provide weekend training.
A teacher may offer online tuition.
A designer may work with small businesses.
Use additional income to strengthen your financial position instead of automatically increasing your lifestyle expenses.
18. Invest in Yourself to Improve Your Earning Capacity
One of the most valuable investments is improving your knowledge and skills.
A qualification, professional certification, or practical skill can potentially improve your career opportunities.
However, spending money on courses does not automatically guarantee a higher salary.
Select learning opportunities carefully.
Identify Skills That Can Improve Your Career
Ask yourself:
- Which skills are currently required in my industry?
- What qualifications do better-paying roles require?
- Can I improve my communication skills?
- Can I learn a new technical tool?
- Is there an opportunity to move into a specialized role?
- Can I build a portfolio demonstrating my abilities?
Set an Annual Learning Budget
You could allocate a small amount every month towards professional development.
For example:
- Online courses.
- Books.
- Certification examinations.
- Professional workshops.
- Industry events.
- Practical projects.
The best investment is one that improves your ability to create value and earn income.
19. Avoid Common Financial Mistakes That Prevent Wealth Creation
Even people who earn a reasonable salary can struggle financially because of poor money-management decisions.
Recognizing these mistakes can help you avoid unnecessary setbacks.
Mistake 1: Waiting Until You Earn More
Many people believe they will start investing after receiving a promotion.
However, promotions can take time, and expenses may increase along with salary.
Better approach: Start with a manageable amount today and increase contributions when your income improves.
Mistake 2: Spending First and Saving Later
Saving whatever remains at the end of the month often produces inconsistent results.
Better approach: Automate savings immediately after receiving your salary.
Mistake 3: Ignoring Emergency Savings
Investing every available rupee in market-linked products can leave you financially vulnerable.
Better approach: Build an emergency fund before taking unnecessary investment risks.
Mistake 4: Investing Without Understanding Risk
Some investors purchase products simply because friends or relatives recommend them.
Better approach: Understand the product, investment objective, liquidity, costs, and potential losses before investing.
Mistake 5: Chasing Quick Profits
Trading tips, speculative investments, and unrealistic return promises can lead to significant losses.
Better approach: Focus on long-term financial goals and diversified investment strategies.
Mistake 6: Taking Too Many Loans
Multiple EMIs can reduce your ability to save and invest.
Better approach: Borrow only when necessary and evaluate the full repayment cost.
Mistake 7: Ignoring Insurance
A lack of adequate health or life insurance can expose your savings to major financial risks.
Better approach: Evaluate insurance according to your family’s actual protection requirements.
Mistake 8: Constantly Comparing Yourself With Others
Comparing your salary, house, car, or lifestyle with friends and colleagues can encourage unnecessary spending.
Better approach: Measure your financial progress against your own goals.
Mistake 9: Ignoring Taxes and Investment Costs
Investment returns should be evaluated after considering applicable taxes, fund expenses, transaction costs, and other charges.
Better approach: Understand the tax treatment of every major investment before committing money.
Mistake 10: Stopping Investments During Every Market Decline
Equity markets experience fluctuations.
Making emotional decisions during market declines can disrupt a long-term investment strategy.
Better approach: Review your financial goals, asset allocation, and risk capacity before making changes.
Do not continue an unsuitable investment merely because you are investing for the long term. The underlying product must still match your objectives.
20. Best Practices for Building Wealth on an Average Salary
Developing a sustainable wealth-building system requires consistency.
The following practices can help you stay financially disciplined.
1. Automate Your Savings
Set up recurring transfers to your savings account or suitable investment products.
2. Review Your Expenses Every Month
Identify unnecessary subscriptions, frequent impulse purchases, and avoidable charges.
3. Maintain Separate Financial Accounts
Consider using separate accounts or clearly identified savings arrangements for:
- Daily expenses.
- Emergency funds.
- Short-term goals.
- Long-term savings.
This can make your money easier to manage.
4. Review Your Investments Periodically
Check whether your investments continue to match your goals and risk tolerance.
Avoid constantly changing investments based on short-term market movements.
5. Keep Your Financial Documents Organized
Maintain records of:
- Bank accounts.
- Insurance policies.
- Investment statements.
- Loan agreements.
- Tax documents.
- Nominee details.
This makes financial administration easier.
6. Review Your Nominees
Ensure that nominee information is updated where applicable.
Also maintain clear records so your family can understand your financial arrangements.
7. Avoid Unnecessary Financial Products
Do not purchase complicated products simply because someone promises high returns or tax savings.
Understand every product before investing.
8. Increase Savings Gradually
A small improvement maintained consistently is often more practical than an ambitious target that you abandon after a few months.
21. A Practical 12-Month Plan to Start Building Wealth
If you are unsure where to begin, follow this simple one-year roadmap.
Month 1: Understand Your Financial Position
- Calculate your monthly take-home salary.
- List your regular expenses.
- Record all outstanding loans.
- Calculate your current savings.
- Estimate your net worth.
Month 2: Prepare a Monthly Budget
- Choose a budgeting method.
- Identify unnecessary expenses.
- Set a realistic savings target.
- Separate essential and lifestyle spending.
Month 3: Start an Emergency Fund
- Open or identify a suitable savings arrangement.
- Automate monthly contributions.
- Set your initial emergency fund target.
Month 4: Review Existing Debt
- List all loan balances.
- Compare interest rates.
- Prioritize expensive debt.
- Avoid unnecessary new EMIs.
Month 5: Review Insurance
- Check your existing health insurance.
- Evaluate life insurance needs if your family depends on your income.
- Understand policy exclusions and coverage.
Month 6: Start Learning About Investments
Study the basics of:
- Mutual funds.
- SIPs.
- Index funds.
- PPF.
- EPF.
- NPS.
- Fixed deposits.
Understand the difference between market-linked and guaranteed or contractually defined returns.
Month 7: Start Your First Investment
If your emergency savings and high-interest debt situation permit, start with a manageable investment amount.
For example, you could begin with ₹500 or ₹1,000 per month in a suitable product.
Month 8: Review Your Financial Goals
Check whether your short-term and long-term targets are realistic.
Adjust your monthly contribution if necessary.
Month 9: Explore Additional Income
Identify one side-income opportunity or professional skill that may improve your earning potential.
Month 10: Increase Your Savings Rate
Try increasing your savings by a small amount.
You can redirect money saved through expense reduction or additional income.
Month 11: Review Your Investment Portfolio
Check whether your investment allocation remains appropriate.
Avoid making unnecessary changes simply because markets have moved up or down.
Month 12: Calculate Your Net Worth Again
Compare your current financial position with the beginning of the year.
Review:
- Total savings.
- Total investments.
- Emergency fund balance.
- Outstanding debt.
- EPF or retirement savings.
- Net worth.
This annual review helps you understand whether your financial habits are producing progress.
22. Practical Wealth-Building Examples for Average-Salary Earners
Let’s look at how different individuals could approach wealth creation.
Example A: A Young Professional Earning ₹25,000
A young employee earns ₹25,000 per month.
They live with family and have relatively low housing expenses.
Their priorities could be:
- Build an emergency fund.
- Avoid unnecessary credit card debt.
- Start a small SIP if appropriate.
- Improve professional skills.
- Increase investment contributions after salary increments.
An initial investment of ₹1,000 per month may be enough to establish a consistent habit.
As income grows, the employee can gradually increase the amount.
Example B: A Married Couple Earning ₹50,000 Together
A household earns ₹50,000 per month.
They manage rent, groceries, transportation, family expenses, and savings.
Their priorities may include:
- Joint household budgeting.
- Adequate health insurance.
- Emergency savings.
- Retirement contributions.
- Children’s future education.
- Managing existing loans.
They could maintain separate goal-based savings arrangements while planning major household decisions together.
Example C: A Person Earning ₹40,000 With Existing Loans
An employee earns ₹40,000 but has several outstanding debts.
In this situation, investing aggressively may not be appropriate.
The first priorities should be:
- Maintain a basic emergency reserve.
- Pay all required EMIs on time.
- Repay high-interest debt.
- Avoid additional unnecessary borrowing.
- Gradually increase long-term investments.
The objective is to improve financial stability before pursuing higher investment risk.
Example D: A Person Earning ₹35,000 and Supporting Their Parents
Someone supporting their parents may have higher monthly responsibilities.
Their budget should account for:
- Household contributions.
- Medical expenses.
- Family insurance.
- Emergency savings.
- Personal financial goals.
- Retirement planning.
A lower investment amount is acceptable if family obligations require more of the income.
Consistency matters more than following an unrealistic savings percentage.
23. How Much Should You Invest Every Month to Build Wealth?
There is no single correct investment amount for everyone.
Your monthly investment should depend on:
- Income.
- Household expenses.
- Existing debt.
- Financial dependants.
- Emergency savings.
- Insurance coverage.
- Investment timeline.
- Risk tolerance.
Here is an illustrative comparison of monthly investment amounts.
Assuming a hypothetical annualized return of 10%, compounded monthly:
| Monthly investment | 10 years | 20 years |
|---|---|---|
| ₹500 | ₹1.03 lakh | ₹3.80 lakh |
| ₹1,000 | ₹2.05 lakh | ₹7.59 lakh |
| ₹2,000 | ₹4.10 lakh | ₹15.19 lakh |
| ₹3,000 | ₹6.15 lakh | ₹22.78 lakh |
| ₹5,000 | ₹10.24 lakh | ₹37.97 lakh |
These are rounded mathematical illustrations, not guaranteed returns or investment forecasts.
The key takeaway is that regular contributions over long periods can make a meaningful difference.
However, you should not invest money needed for rent, groceries, essential bills, or emergency expenses simply to reach a target.
24. Plan for Retirement Even If You Earn an Average Salary
Retirement planning should not be postponed until your 40s or 50s.
The earlier you start, the more time your investments may have to grow.
Estimate Your Retirement Expenses
Start by calculating your current monthly household expenses.
Then consider how these expenses may change after retirement.
You may spend less on commuting or work-related costs, but healthcare and other expenses may increase.
Also consider inflation.
Use Existing Retirement Benefits
Eligible salaried employees should understand their EPF benefits.
You may also consider PPF or NPS, depending on your retirement objectives and applicable rules.
Avoid relying entirely on one retirement product.
Avoid Withdrawing Retirement Savings for Unnecessary Purchases
Retirement funds are intended to support your financial needs later in life.
Frequent withdrawals can reduce the amount available for long-term financial security.
Use retirement savings only after considering the consequences and applicable rules.
25. Understand Tax Planning While Building Wealth
Tax planning is another important part of personal finance.
The goal should be to make informed financial decisions rather than purchasing products solely to claim deductions.
Understand the Applicable Tax Regime
India has different personal income-tax regimes with different provisions.
The availability of deductions, exemptions, and benefits depends on the applicable tax regime and current law.
Compare both regimes based on your actual income and eligible claims.
Understand Tax Treatment of Investments
Different investments may receive different tax treatment.
For example:
- Equity mutual funds.
- Debt mutual funds.
- Bank fixed deposits.
- PPF.
- EPF.
- NPS.
- Gold investments.
Tax rules can change.
Therefore, check the current provisions before making investment or withdrawal decisions.
Keep Financial Records
Maintain:
- Investment statements.
- Interest certificates.
- Salary documents.
- Insurance premium receipts.
- Eligible deduction records.
- Capital gains statements.
Organized records can make tax filing and financial reviews easier.
For complicated financial situations, consult a qualified tax professional.
26. How to Stay Motivated During Your Wealth-Building Journey
Building wealth takes time.
You may not notice significant changes during the first few months.
However, consistent financial habits can gradually improve your position.
Set Small Financial Milestones
Instead of focusing only on a large retirement target, celebrate practical milestones.
For example:
- First ₹10,000 saved.
- First ₹50,000 emergency fund.
- First ₹1 lakh invested.
- First debt-free year.
- First increase in monthly investment.
- First positive net-worth milestone.
These achievements can help maintain motivation.
Avoid Constantly Checking Investment Returns
Checking your portfolio several times every day may encourage emotional decisions.
For long-term investments, periodic reviews are generally more useful than reacting to daily price changes.
Focus on What You Can Control
You cannot control the stock market, inflation, interest-rate decisions, or economic conditions.
But you can control:
- Your savings habits.
- Your expenses.
- Your debt decisions.
- Your investment discipline.
- Your professional development.
- Your financial goals.
Concentrate on these areas.
27. Future Financial Trends Average-Salary Earners Should Understand
Financial planning continues to evolve as technology, employment patterns, and investment products change.
Understanding these developments can help you make better decisions.
Digital Investment Platforms
Digital platforms have made it easier to access mutual funds, stocks, deposits, and other financial products.
However, convenience does not replace investment knowledge.
Always verify the platform, regulatory status, fees, and product details.
Financial Education Through Online Resources
People can now learn about budgeting, investing, taxes, and retirement through educational websites and online courses.
Use credible sources and verify important financial information.
Be cautious of influencers who promise guaranteed profits or promote products without explaining risks.
Artificial Intelligence in Personal Finance
AI-based tools can help people:
- Categorize expenses.
- Prepare budgets.
- Track financial goals.
- Understand investment concepts.
- Organize financial information.
However, AI-generated financial information can be incomplete or inaccurate.
Never share passwords, OTPs, account credentials, or confidential financial information with unverified tools.
Changing Employment Patterns
Freelancing, remote employment, contract work, and entrepreneurship are changing how people earn money.
Individuals with variable income may need larger emergency reserves and more flexible financial plans.
A financial strategy should reflect the stability of your income rather than assuming that every month will be identical.
28. Expert Tips for Building Wealth Faster on an Average Salary
You do not need complicated investment strategies to improve your financial position.
The following practical suggestions can help.
Tip 1: Increase Your Income Every Few Years
Develop skills, seek promotions, and explore better career opportunities.
Tip 2: Save Every Salary Increment
Do not allow lifestyle expenses to absorb your entire income increase.
Tip 3: Invest According to Your Goals
A retirement investment and a one-year savings goal require different approaches.
Tip 4: Keep Your Investment Portfolio Understandable
Avoid purchasing too many financial products without understanding their purpose.
Tip 5: Avoid High-Interest Borrowing
Unnecessary debt can reduce your ability to accumulate assets.
Tip 6: Protect Your Family Financially
Review health insurance, term insurance, and emergency savings.
Tip 7: Learn About Financial Products Before Investing
Understand the costs, risks, liquidity, tax implications, and withdrawal conditions.
Tip 8: Review Your Net Worth Annually
Measure your financial progress instead of judging it by your monthly salary alone.
Tip 9: Do Not Chase Every New Investment Trend
A product being popular does not make it suitable for your financial situation.
Tip 10: Remain Consistent
A realistic financial plan that you follow for years is more useful than an ambitious plan that you abandon after a few months.
Frequently Asked Questions (FAQs)
1. Can I build wealth on an average salary in India?
Yes. Building wealth is possible even with an average salary if you manage your expenses, save consistently, invest according to your financial goals, and avoid unnecessary debt.
You do not need a large starting amount. Begin with a manageable contribution and increase it as your income grows.
2. How much money should I save every month from my salary?
A commonly used guideline is to save around 20% of your take-home income.
However, this is not compulsory.
If you earn ₹25,000, even saving ₹1,000 to ₹2,000 consistently can be a useful starting point. Your savings target should reflect your household expenses, debt, and financial responsibilities.
3. How can I invest ₹1,000 per month to build wealth?
You can explore suitable mutual fund SIPs, recurring deposits, or other eligible savings and investment products.
For long-term market-linked investments, consider your risk tolerance and investment horizon before selecting a mutual fund.
Remember that mutual fund returns are not guaranteed.
4. Which investment is best for salaried people in India?
There is no single best investment for everyone.
EPF may support eligible employees’ retirement savings. PPF can be considered for long-term savings. Mutual funds may provide market-linked growth opportunities. Fixed deposits can serve short-term savings needs.
Your choice should depend on your financial goals, risk tolerance, liquidity requirements, and tax situation.
5. Is SIP enough to become wealthy?
SIPs can be a useful part of a long-term investment strategy, but they are not a complete wealth-building plan.
You also need budgeting, emergency savings, debt management, adequate insurance, income growth, and suitable financial planning.
6. How long does it take to build wealth on an average salary?
The timeline depends on your income, savings rate, investment returns, financial goals, and expenses.
Building meaningful wealth generally requires consistent effort over many years.
Starting early and gradually increasing your savings can improve your long-term financial position.
7. Should I clear my loans before starting investments?
It depends on the type of loan and its interest rate.
High-interest debt, such as revolving credit card debt, generally deserves priority.
For lower-interest loans, you may be able to balance repayment and long-term investing, depending on your cash flow and risk tolerance.
Always maintain enough money for essential expenses and emergency needs.
8. What is the biggest mistake people make when building wealth?
One major mistake is delaying financial planning until they earn more money.
Other common mistakes include unnecessary borrowing, lifestyle inflation, ignoring emergency funds, chasing quick profits, and investing without understanding risk.
Starting with small, consistent financial habits can help avoid these problems.
Conclusion: Start Building Wealth With the Salary You Have Today
Building wealth on an average salary is not about becoming rich overnight. It is about making thoughtful financial decisions repeatedly over a long period.
You do not need a huge salary, an expensive investment portfolio, or a complicated financial strategy to get started.
You need to understand your income, control unnecessary expenses, build an emergency fund, manage debt, protect your family, and invest consistently according to your financial goals.
Remember these essential principles:
- Spend less than you earn whenever your circumstances allow.
- Save before spending.
- Start investing with an affordable amount.
- Understand compounding and the value of time.
- Increase your investments when your salary grows.
- Avoid unnecessary loans and lifestyle inflation.
- Invest in skills that can improve your income.
- Review your financial progress regularly.
- Make decisions based on your goals rather than social pressure.
If you earn ₹20,000, ₹30,000, ₹40,000, or ₹50,000 per month, you can begin improving your financial position today.
Your first step does not need to be a large investment. It could simply be tracking your expenses, saving ₹500, starting an emergency fund, or clearing an expensive loan.
The most important thing is to begin with a realistic plan and follow it consistently.
Your salary determines how much money you receive, but your financial habits influence how much wealth you can build. Start with what you have, improve your financial knowledge, and take one meaningful step towards financial independence today.
Call to Action: Take a few minutes today to calculate your monthly income, expenses, savings, and outstanding debt. Set your first savings target and create a simple monthly investment plan. Share this article with friends and family who want to build wealth, manage money better, and achieve long-term financial security.
https://sarkariyojana24.co.in/
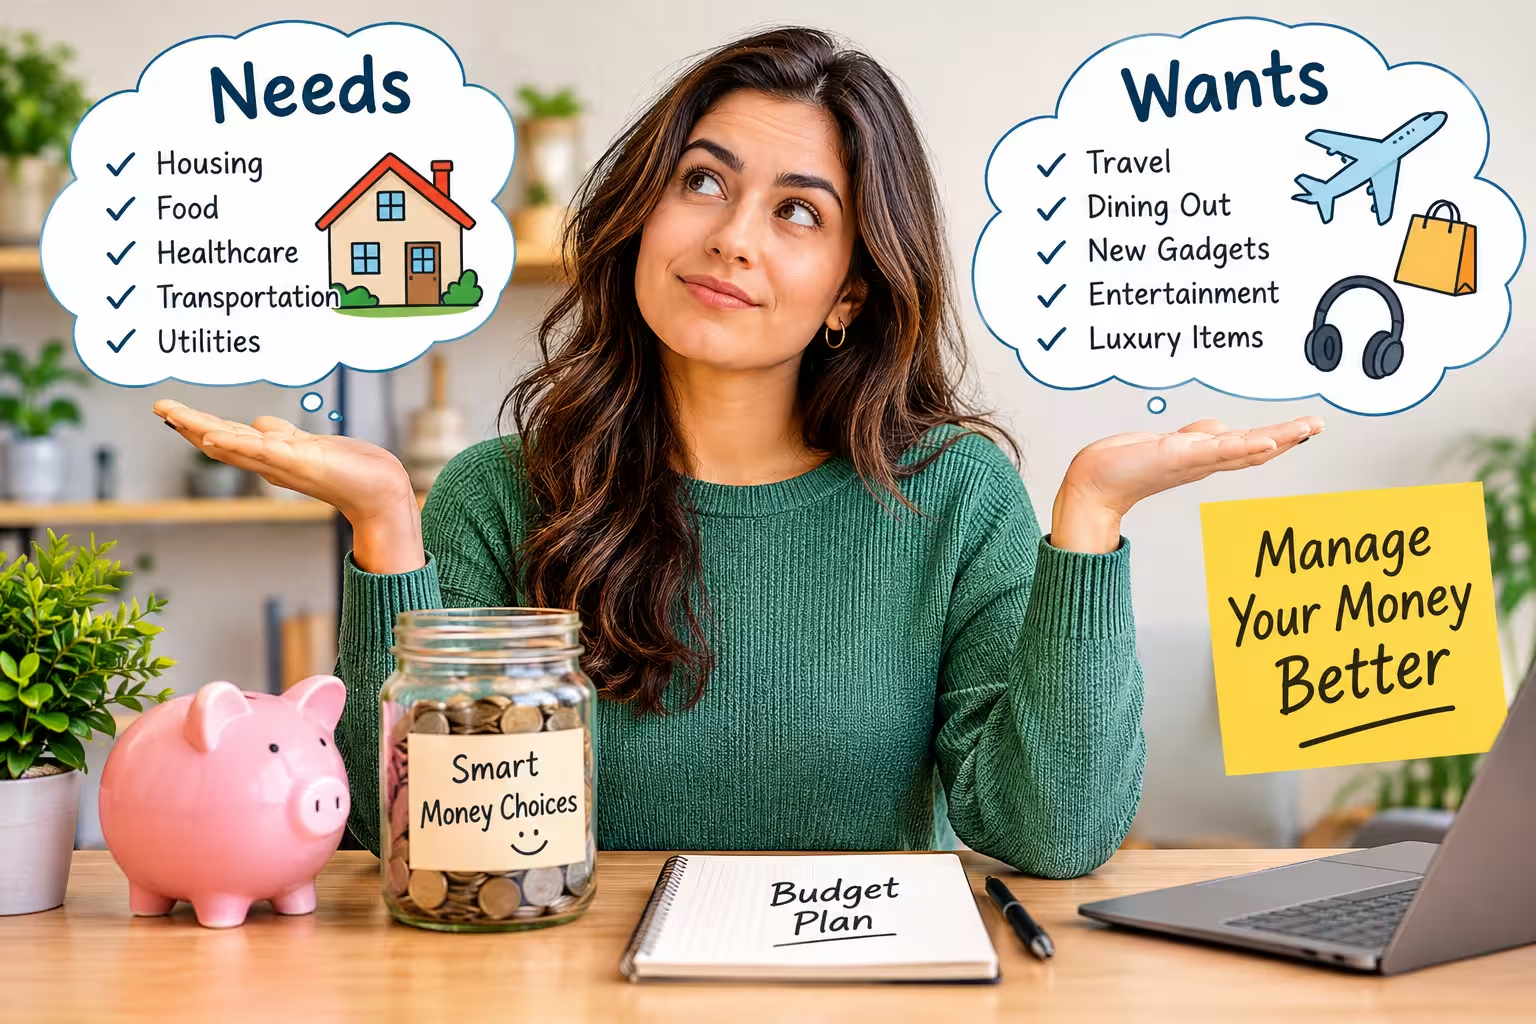
Needs vs Wants: How to Manage Your Money Better and Build Smarter Financial Habits
Share this content:
Post Comment