RBI Bulk FD Rules From October 1, 2026: New Disclosure Norms, FD Rates, Loans and EMI Impact Explained
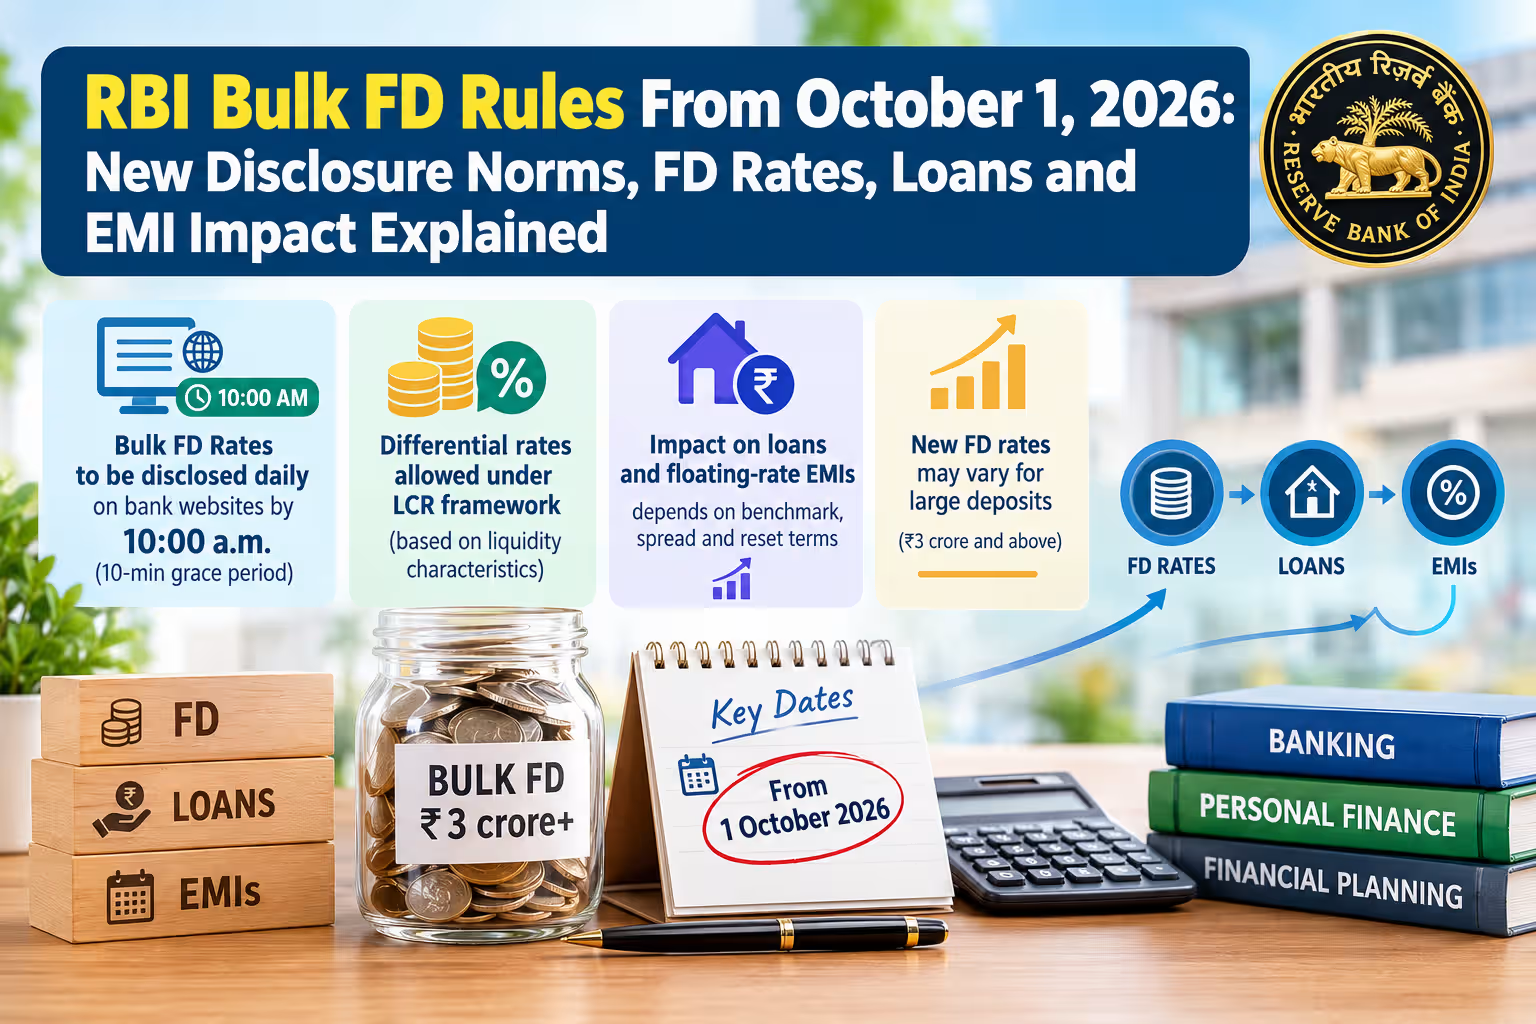
RBI bulk FD rules October 2026 Bank fixed deposits have long been one of India’s most popular savings products, particularly for people who value predictable returns and relatively simple investment structures. But from October 1, 2026, RBI’s revised rules for bulk deposit interest rates and disclosures have changed how large fixed deposits are priced and communicated by banks.
The change is significant for large depositors because banks are now required to disclose applicable bulk-deposit interest rates on their websites every business day by 10:00 a.m., with a 10-minute grace period, while the framework also gives banks greater flexibility to differentiate rates for bulk deposits based on liquidity characteristics under the Liquidity Coverage Ratio (LCR) framework.
For most ordinary FD investors, these rules do not mean that every fixed deposit suddenly gets a new interest rate. The direct change is concentrated around large or “bulk” deposits. However, the broader environment matters because banks manage deposits and loans together. Deposit costs influence a bank’s funding profile, while the RBI’s monetary-policy decisions influence many floating-rate loans and EMIs.
That makes October an important month for both savers and borrowers.
There is also an important correction to a common interpretation: the bulk-FD disclosure changes themselves do not directly reset floating-rate home loans or personal-loan EMIs. Those loan rates depend on the applicable benchmark, such as an external benchmark or another permitted reference rate, plus the contractual spread. The connection between deposits, loans and EMIs is therefore indirect rather than automatic. RBI rules require new floating-rate personal and retail loans offered by banks to be linked to specified external benchmarks, and the reset mechanism depends on the loan contract.
This guide explains the October 2026 RBI changes in plain language, who they affect, what bulk FD investors should check before locking in money, and why the wider interest-rate cycle matters for both deposits and borrowing.
RBI bulk FD rules October 2026 – What Changed From October 1, 2026?
The Reserve Bank of India issued the Reserve Bank of India (Commercial Banks – Interest Rate on Deposits) Second Amendment Directions, 2026 on July 30, 2026. The directions took effect from October 1, 2026.
The revised framework makes several important changes to the way deposit rates, particularly bulk-deposit rates, are disclosed and priced.
The key changes include:
- Banks must disclose deposit interest rates in advance on their websites.
- Bulk-deposit interest rates must be displayed at 10:00 a.m. on every business day, with a grace period until 10:10 a.m.
- Interest rates for deposits of similar amounts accepted on the same date must generally be uniform across branches and customers.
- Banks are permitted to offer differential interest rates on bulk deposits by considering applicable LCR run-off rates.
- The changes apply from October 1, 2026.
- Similar amendments were issued for certain other regulated bank categories, including small finance banks and regional rural banks, with category-specific rules.
The result is a framework that combines greater transparency with more risk-sensitive pricing flexibility.
What Is a Bulk Fixed Deposit?
A bulk deposit is a large single rupee term deposit that crosses the threshold specified under RBI regulations for the relevant type of bank.
For scheduled commercial banks, excluding regional rural banks, and for small finance banks, the current definition generally covers single rupee term deposits of ₹3 crore and above. Regional rural banks and local area banks have a ₹1 crore threshold under the applicable framework.
That means a person putting ₹20 lakh into an FD is generally not dealing with the same bulk-deposit framework as a company placing ₹5 crore with a bank.
Simple examples
Consider three hypothetical deposits with a commercial bank:
- ₹10 lakh FD — ordinary retail-sized deposit
- ₹75 lakh FD — large, but below the ₹3 crore bulk threshold
- ₹5 crore FD — bulk deposit
The third deposit falls within the bulk-deposit framework applicable to scheduled commercial banks.
This distinction matters because banks may have different pricing structures for large deposits.
Why Did RBI Change the Bulk FD Rules?
The RBI’s objective is closely connected to transparency, consistency and liquidity management.
Banks receive deposits from millions of customers and use those funds as an important part of their funding base.
But not all deposits behave in exactly the same way.
A small household savings balance may be relatively stable.
A large institutional deposit, on the other hand, can represent a substantial amount of money that could potentially move when market conditions or the depositor’s needs change.
From a bank’s perspective, that creates a liquidity consideration.
The revised framework allows banks to take applicable run-off characteristics under the LCR framework into account when pricing eligible bulk deposits.
At the same time, RBI has tightened disclosure requirements so depositors can see the rates banks are offering.
The combination is important:
More transparency for deposit pricing + greater flexibility to account for liquidity risk.
What Is the New Bulk FD Disclosure Rule?
The most visible change for depositors is the daily disclosure requirement.
From October 1, banks must publish applicable bulk-deposit interest rates on their websites every business day.
The stated timing is:
10:00 a.m.
with a grace period of:
10 minutes
meaning the disclosure should be available no later than 10:10 a.m. on a business day.
This gives large depositors a clearer reference point when comparing rates.
Previously, a large depositor could negotiate or receive a rate through bank-level processes that were not necessarily visible to the broader market.
The new framework makes the applicable schedule more transparent.
Does RBI Ban Banks From Giving Different Bulk FD Rates?
No.
This is an important point.
The new framework does not simply impose one identical interest rate on every bulk deposit regardless of circumstances.
Instead, RBI has permitted banks to offer differential interest rates on bulk deposits by considering applicable run-off rates under the LCR framework.
This means banks have greater flexibility to distinguish between eligible bulk deposits based on liquidity characteristics.
However, the framework still retains an important principle of uniformity.
For deposits of a similar amount accepted on the same date, the applicable interest rate should not be arbitrarily different from one branch to another or between customers merely because of individual negotiation outside the permitted framework.
This is designed to reduce discriminatory or opaque pricing.
What Does “Uniform Interest Rate” Mean?
Suppose a bank publishes a particular rate for a defined bulk-deposit category on a particular day.
If two customers place comparable deposits that fall into the same applicable category on that day, the bank cannot simply give one customer a materially different rate because that customer happened to negotiate harder at one branch.
The exact pricing categories and permitted differentiation depend on the bank’s board-approved framework and applicable RBI rules.
The objective is consistency.
Why is this useful?
It helps create:
- better price visibility,
- greater comparability,
- reduced room for arbitrary pricing,
- clearer audit trails,
- stronger regulatory oversight.
It can also make conversations between depositors and banks more straightforward.
How LCR Can Affect Bulk FD Pricing
The Liquidity Coverage Ratio, or LCR, is a banking liquidity requirement designed to ensure that banks maintain enough high-quality liquid assets to withstand a stressed liquidity scenario.
In simple terms, the LCR asks a bank to have sufficient readily available liquid assets to cover expected net cash outflows over the relevant stress period.
Different categories of funding can have different assumed outflow characteristics.
A deposit that is expected to be less stable under stress may receive a higher assumed run-off rate.
That matters to a bank because higher potential outflows create greater liquidity requirements.
The revised RBI framework allows banks to consider these differential run-off characteristics when setting rates on eligible bulk deposits.
Why Would Liquidity Risk Affect an FD Interest Rate?
Consider a simplified example.
Imagine Bank A receives two large deposits:
- Deposit A: ₹5 crore from a stable source
- Deposit B: ₹5 crore from a funding category with a higher assumed liquidity run-off
Both deposits are ₹5 crore.
But from the bank’s liquidity-management perspective, they may not have exactly the same characteristics.
If the applicable RBI framework allows the bank to consider those differences, the bank may structure its bulk-deposit pricing accordingly.
This is not necessarily about one customer being “better” than another.
It is about the bank’s regulatory and liquidity economics.
Does This Mean Ordinary FD Investors Will Get Different Rates?
Usually, the direct impact will be limited for people investing amounts below the bulk-deposit threshold.
Banks already publish different FD rates according to factors such as:
- deposit tenure,
- customer category,
- senior-citizen eligibility where applicable,
- product type,
- deposit size where permitted.
The new bulk-deposit rules specifically matter when a deposit enters the applicable bulk category.
For a household investing ₹5 lakh, ₹10 lakh or ₹20 lakh in a conventional FD, the October 1 bulk-deposit disclosure rules are not the main pricing issue.
However, the wider interest-rate environment still matters.
Why Large Depositors Should Pay Attention
The new framework is particularly relevant to:
- companies,
- trusts,
- institutions,
- large family businesses,
- high-net-worth individuals,
- charitable organizations,
- educational institutions,
- government-related entities,
- corporate treasury departments.
A depositor placing several crores with a bank cannot afford to treat the FD rate as a minor detail.
Even a small difference in annual interest can represent a substantial rupee amount when applied to a large principal.
Example
Suppose ₹5 crore is invested for one year.
At 6.00% interest:
₹5 crore × 6% = ₹30 lakh
At 6.25%:
₹5 crore × 6.25% = ₹31.25 lakh
The difference is:
₹1.25 lakh for one year
This is a simplified illustration and assumes a straightforward annual-interest calculation before considering taxation, compounding structure and the bank’s specific FD terms.
For large depositors, therefore, comparing rates is worthwhile.
How the New Rules Improve Transparency for Bulk FD Investors
The daily disclosure requirement can make rate discovery easier.
Instead of relying only on conversations with relationship managers or branch officials, a large depositor can check the bank’s published schedule.
This provides a documented reference.
Before booking a bulk FD, check:
- The bank’s official website.
- The date of the published rate.
- The relevant deposit amount category.
- The tenure.
- Whether the rate is for callable or non-callable deposits.
- Whether the depositor qualifies for any permitted category.
- Premature-withdrawal conditions.
- Tax implications.
- Maturity instructions.
- Whether the rate is applicable to the exact deposit structure being considered.
The headline rate alone is never enough.
What Is a Non-Callable FD?
A non-callable fixed deposit is a term deposit that generally does not permit premature withdrawal under the conditions applicable to the product.
RBI has previously permitted banks to offer non-callable term deposits subject to applicable minimum amounts and regulatory conditions.
This distinction matters because a higher interest rate can sometimes come with reduced liquidity.
For a large depositor, locking ₹3 crore or more for a fixed period without an easy premature-withdrawal option can create a liquidity problem if funds are needed unexpectedly.
Therefore:
Higher rate does not automatically mean better deposit.
The right FD depends on the depositor’s liquidity requirements, risk tolerance, tax position and investment horizon.
How to Compare Bulk FD Rates From October 2026
A disciplined comparison process can prevent costly mistakes.
Step 1: Determine whether the deposit qualifies as bulk
Check the applicable threshold for your bank category.
For many scheduled commercial banks, the relevant threshold is ₹3 crore for a single rupee term deposit.
Step 2: Check the bank’s daily rate disclosure
Look at the bank’s website and check the latest published bulk-deposit rate.
Step 3: Compare the exact tenure
A 12-month FD and a 24-month FD cannot be compared simply by looking at the headline percentage.
Step 4: Check liquidity conditions
Find out whether premature withdrawal is allowed and what penalty applies.
Step 5: Check payout structure
Compare:
- cumulative FD,
- monthly interest payout,
- quarterly payout,
- annual payout,
- maturity payout.
Step 6: Consider tax
Interest income is taxable according to applicable tax rules.
Step 7: Consider deposit concentration
Do not automatically put all your money with one bank simply because its headline rate is higher.
Does a Higher FD Rate Always Mean a Better Deal?
No.
A higher rate is attractive, but it is only one part of the decision.
Suppose:
Bank A: 6.50%
Bank B: 6.25%
The first rate looks better.
But a depositor should also compare:
- deposit-insurance considerations,
- bank strength,
- tenure,
- premature withdrawal rules,
- liquidity needs,
- interest payout structure,
- tax treatment,
- concentration risk.
For a very large deposit, risk management becomes more important than chasing a marginal rate difference.
Deposit Insurance and Large FDs
Deposit insurance is another area that large FD investors should understand.
The Deposit Insurance and Credit Guarantee Corporation (DICGC) provides deposit insurance subject to the applicable statutory limit and conditions.
The insurance framework should not be interpreted as covering an unlimited amount simply because a depositor has multiple fixed deposits.
Depositors should understand how deposits are aggregated under applicable DICGC rules and how ownership capacity affects coverage.
This is especially relevant when someone is placing several crore rupees.
A large depositor should therefore evaluate the bank itself rather than assuming that every rupee of a multi-crore FD is automatically insured.
Will New Bulk FD Rules Increase FD Interest Rates?
Not necessarily.
The RBI’s new framework does not guarantee that banks will raise bulk FD rates.
It changes the pricing and disclosure framework.
Actual rates continue to depend on factors such as:
- bank funding requirements,
- liquidity conditions,
- loan demand,
- competition,
- monetary policy,
- market interest rates,
- balance-sheet strategy,
- deposit growth requirements.
A bank that urgently needs stable deposits may price them differently from a bank that already has comfortable funding.
The new framework gives banks greater ability to incorporate liquidity characteristics into eligible bulk-deposit pricing.
How FD Rates Are Connected to the Broader Interest-Rate Cycle
Fixed-deposit rates do not exist in isolation.
Banks borrow and raise funds through several channels and deploy those funds into loans and other assets.
When the overall interest-rate environment changes, banks may reassess deposit pricing.
The RBI’s monetary policy is therefore relevant.
As of early October 2026, the policy repo rate was 5.25%, following the RBI’s August 2026 decision to keep it unchanged. The next Monetary Policy Committee meeting is scheduled for October 5–7, with the policy decision due on October 7.
Market expectations ahead of the meeting have included the possibility of a rate increase, but that is an expectation rather than an announced RBI decision. Reuters reported on October 5 that markets and economists were anticipating a possible 25-basis-point increase, while the repo rate remained 5.25% at that point.
That distinction is crucial for personal-finance planning.
What Could Happen to FD Rates if RBI Raises the Repo Rate?
If the RBI increases its policy rate, banks may face a higher overall cost of funds and may reassess lending and deposit rates.
However, the transmission is not always immediate or identical across every bank and product.
A bank could:
- increase selected FD rates,
- leave some FD rates unchanged,
- adjust only certain tenures,
- change bulk-deposit pricing,
- alter lending rates,
- change deposit mix.
Therefore, an RBI rate hike does not automatically mean that every FD rate rises by exactly the same amount.
What Happens to Floating-Rate Loans?
This is where borrowers need to distinguish between RBI’s bulk-FD rules and RBI’s monetary-policy transmission.
The October 1 bulk-deposit amendment does not itself reset your home-loan EMI.
For floating-rate personal or retail loans offered by banks, RBI requires new loans in the relevant categories to be linked to specified external benchmarks, including the RBI policy repo rate or certain specified market benchmarks.
Therefore, if the benchmark changes, the loan rate can change according to the loan’s contractual reset mechanism.
Why Floating-Rate EMI Borrowers Should Watch the RBI Repo Rate
Suppose a home loan has an external benchmark linked to the RBI repo rate.
If the benchmark rises, the loan’s interest rate may rise at the applicable reset.
That can affect either:
- EMI amount,
- loan tenure,
- or both,
depending on the lender’s policy and the borrower’s contractual terms.
RBI’s framework for EMI-based floating-rate personal loans requires regulated entities to communicate the impact of benchmark resets and provide borrowers with information about options when rates rise. RBI’s FAQ states that borrowers should receive information about the impact on EMI or tenor and, during the loan tenure, communication when benchmark movements increase EMI or tenor.
Floating EMI Example
Consider a hypothetical home loan of ₹40 lakh.
Suppose the interest rate is 8.25%.
If the benchmark-linked rate rises by 25 basis points to 8.50%, the borrower could see a higher interest burden.
The exact EMI impact depends on:
- outstanding principal,
- remaining tenure,
- current EMI,
- reset frequency,
- lender methodology,
- whether the lender changes EMI or tenure.
That is why a 25-basis-point change cannot be converted into one universal EMI increase for every borrower.
What Borrowers Should Do Before the Next Rate Reset
If you have a floating-rate loan, check your loan statement and sanction documents.
Look for:
- benchmark name,
- spread,
- reset frequency,
- reset date,
- current interest rate,
- outstanding principal,
- remaining tenure,
- EMI amount.
Then ask your lender:
“What will happen to my EMI or tenure if the benchmark changes by 25 basis points?”
This question is much more useful than simply asking whether interest rates are going up.
Can Banks Change the Spread on a Floating Loan?
A floating-rate loan typically consists of a benchmark plus a spread or margin, subject to the applicable RBI framework and contractual terms.
For existing external-benchmark-linked borrowers, changes in the benchmark do not mean that the bank can freely rewrite every component of the loan whenever it wants.
The contractual spread, reset rules and regulatory requirements matter.
Borrowers should therefore check the loan agreement rather than assuming that every rate movement is entirely at the bank’s discretion.
How FD Rates and Loan Rates Are Connected
There is an economic relationship between deposits and loans, but it is not a simple one-to-one formula.
Banks receive funds through deposits and other funding channels.
They lend those funds to borrowers.
The difference between the return earned on assets and the cost of liabilities is an important part of bank economics.
If deposit costs rise, banks may face pressure on their funding costs.
If loan rates do not adjust correspondingly, margins can be affected.
Conversely, if loan demand is weak, a bank may not necessarily raise deposit rates simply because the RBI changes the policy rate.
This is why the relationship should be described as indirect and market-dependent, not automatic.
Why October 2026 Is Important for Savers and Borrowers
October combines two developments:
1. Bulk FD pricing transparency
Large depositors now have clearer access to published bulk-deposit rates.
2. A live monetary-policy decision
The RBI MPC is meeting October 5–7, with the policy outcome scheduled for October 7.
These events affect different parts of personal finance.
The first directly concerns deposit-rate disclosure and bulk-deposit pricing.
The second can influence the broader interest-rate environment.
Together, they make October an important month to review both savings and borrowing decisions.
Practical Guide for Large FD Investors
If you have ₹3 crore or more available for an FD, do not simply search for the highest advertised number.
Use a structured process.
1. Check whether the deposit is classified as bulk
Confirm the applicable bank category and threshold.
2. Review the daily published rate
Check the bank’s website around the required disclosure window.
3. Compare at least three banks
Compare similar:
- principal,
- tenure,
- payout structure,
- withdrawal conditions.
4. Check whether the deposit is callable
A slightly higher rate may not compensate for losing liquidity.
5. Examine the bank’s terms
Read the deposit agreement before transferring funds.
6. Consider concentration
Avoid making a large financial decision solely on the basis of the highest rate.
7. Calculate post-tax returns
A 6.5% FD does not necessarily provide a 6.5% post-tax return.
8. Review maturity planning
Know exactly when the FD matures and what happens if you do nothing.
Practical Guide for Ordinary FD Investors
If your FD is below the bulk threshold, you do not need to overreact to headlines about bulk-deposit rules.
Instead, focus on:
- current retail FD rates,
- tenure,
- senior-citizen benefit if applicable,
- premature withdrawal rules,
- tax,
- bank safety,
- deposit insurance,
- liquidity requirements.
You should also compare the rate with the inflation environment and your financial goals.
Should You Lock in a Long-Term FD Now?
There is no universal answer.
The right decision depends on your expectations, liquidity requirements and financial goals.
If you believe rates could rise further, locking the entire amount into a long-term FD today could mean missing potentially higher future rates.
If rates fall, however, locking an attractive rate for a longer period could prove useful.
Because future interest rates are uncertain, many savers consider a laddering strategy rather than putting the entire amount into one maturity.
What Is FD Laddering?
FD laddering means dividing your investment across multiple deposits with different maturity dates.
For example, instead of putting ₹10 lakh into one five-year FD, an investor might divide it into several deposits with different maturities.
The exact structure can vary.
The advantages can include:
- regular liquidity,
- reduced reinvestment concentration,
- flexibility when rates change,
- easier cash-flow planning.
For large deposits, laddering can be combined with diversification across institutions, subject to the investor’s circumstances.
Common Mistakes to Avoid With Bulk FDs
Mistake 1: Looking only at the headline rate
A 0.25% difference can be less important than withdrawal restrictions or concentration risk.
Mistake 2: Ignoring the daily rate disclosure
From October 1, bulk-deposit rates have a defined daily disclosure requirement.
Mistake 3: Assuming every large deposit gets the same rate
The revised framework permits certain differential pricing based on liquidity characteristics.
Mistake 4: Confusing bulk FD rules with retail FD rules
A ₹5 lakh FD is not treated the same way as a ₹5 crore bulk deposit.
Mistake 5: Assuming RBI’s bulk FD rule directly changes home-loan EMIs
It does not.
Loan EMIs depend on the applicable loan benchmark and reset mechanism.
Mistake 6: Ignoring taxes
The headline FD rate is not the same as your post-tax return.
Mistake 7: Ignoring liquidity
Large deposits can create a problem if the money is needed before maturity.
Mistake 8: Putting all funds into one institution
Large depositors should think about concentration risk and applicable deposit-insurance limits.
Expert Tips for Managing Money in a Changing Rate Environment
Keep an eye on the policy rate
The RBI repo rate remains an important reference point for the broader financial system.
Review floating loans after every major policy decision
Do not wait until the EMI suddenly changes.
Compare FD rates periodically
Banks adjust their deposit pricing according to their own funding requirements and market conditions.
Use FD laddering for large amounts
This can reduce dependence on one maturity date.
Separate emergency funds from long-term deposits
Do not lock emergency money into a product that is difficult or costly to withdraw.
Calculate real returns
Compare interest after tax with inflation and your financial objective.
Read the fine print
The interest rate is only one term of an FD contract.
What Should Businesses Know About Bulk FD Rules?
Corporate treasury teams have a particularly strong reason to monitor the October changes.
A business may hold large temporary cash balances because of:
- receivables,
- project payments,
- seasonal cash flows,
- acquisitions,
- inventory cycles,
- tax payments,
- capital expenditure.
If those balances are placed into term deposits, the treasury team should compare the bank’s published bulk-deposit rates and liquidity conditions.
A treasury checklist
Before placing a bulk FD:
- Verify the latest rate.
- Verify the applicable category.
- Confirm the rate’s validity date.
- Check maturity.
- Review premature withdrawal terms.
- Check callable/non-callable status.
- Confirm documentation.
- Consider bank concentration.
- Record the transaction for audit purposes.
- Review whether the deposit fits the company’s liquidity forecast.
The new disclosure rules can make this process more transparent and easier to document.
What Does the RBI Change Mean for Senior Citizens?
For senior citizens, the most relevant point is that bulk-deposit rules should not automatically be confused with ordinary senior-citizen FD pricing.
Banks may provide permitted additional interest to eligible senior citizens under their deposit policies.
But whether a particular large deposit receives a senior-citizen benefit depends on the bank’s product rules and applicable RBI framework.
A senior citizen with a multi-crore deposit should therefore ask the bank to explain:
- the standard bulk rate,
- applicable senior-citizen benefit, if any,
- whether the deposit qualifies,
- whether the rate is uniform under the relevant category,
- and the premature withdrawal terms.
What About NRI Depositors?
The revised framework also addresses applicable rupee deposits of non-residents in relation to the LCR-linked differential-rate provision.
The commercial-bank amendment specifically provides for consideration of applicable run-off rates for rupee deposits of non-residents as well.
However, NRIs should not assume that domestic resident FD rules apply identically to every NRE or NRO product.
The account type, currency, tax treatment, repatriation rules and deposit terms matter.
An NRI should compare the specific product rather than relying on a general bulk-FD headline.
Frequently Asked Questions
1. What changed in RBI bulk FD rules from October 1, 2026?
From October 1, 2026, revised RBI directions require banks to disclose applicable bulk-deposit interest rates on their websites at 10:00 a.m. every business day, with a 10-minute grace period. The framework also allows banks to offer differential bulk-deposit rates based on applicable LCR run-off characteristics.
2. What is considered a bulk deposit?
For scheduled commercial banks excluding regional rural banks, and for small finance banks, a bulk deposit is generally a single rupee term deposit of ₹3 crore and above. Regional rural banks and local area banks have a ₹1 crore threshold under their applicable directions.
3. Do banks have to publish bulk FD rates every day?
Yes. Under the revised commercial-bank framework, bulk-deposit rates must be disclosed on the bank’s website at 10:00 a.m. on each business day, with a grace period until 10:10 a.m.
4. Can banks offer different interest rates on bulk deposits?
Yes, but within the revised regulatory framework. Banks have been given flexibility to offer differential rates on bulk deposits by considering applicable run-off rates under the LCR framework. The framework also requires uniform treatment for comparable deposits accepted on the same date across branches and customers.
5. Will the new bulk FD rules directly increase my home-loan EMI?
No. The bulk-deposit amendment does not itself reset home-loan EMIs. Floating-rate loan changes depend on the loan’s applicable benchmark, spread and reset mechanism. New floating-rate personal and retail loans from banks are subject to RBI’s external-benchmark framework.
6. Will FD interest rates increase after October 1?
Not necessarily. The new rules change the disclosure and pricing framework for eligible deposits; they do not mandate a universal increase in FD rates. Individual banks determine their rates within the applicable RBI framework.
7. Should I invest in a bulk FD just because the rate is higher?
Not automatically. Compare the rate with liquidity conditions, premature-withdrawal rules, tenure, tax impact, bank concentration and applicable deposit-insurance coverage before making a large investment.
8. Why does the RBI allow LCR-linked pricing?
Large deposits can have different liquidity characteristics. The revised framework allows banks to consider applicable run-off rates under the LCR framework when pricing eligible bulk deposits. This gives banks more flexibility while requiring greater rate transparency.
What Savers and Borrowers Should Do Now
The October 2026 banking changes are a good reason to review your financial arrangements, but not a reason to make rushed decisions.
If you are a large FD investor:
Check your bank’s daily bulk-deposit rate disclosure, compare comparable tenures and review liquidity conditions before booking or renewing a large FD.
If you are an ordinary FD investor:
Focus on the retail rate applicable to your deposit rather than assuming the bulk-deposit rules change your FD automatically.
If you have a floating-rate loan:
Check the benchmark, spread and reset date in your loan documents. Monitor RBI policy decisions and your lender’s communication.
If you are managing a business treasury:
Build the new daily rate-disclosure process into your cash-management and investment workflow.
The Bigger Picture for Personal Finance in October 2026
The RBI’s bulk-deposit changes are ultimately about making deposit pricing more transparent while giving banks additional flexibility to account for liquidity risk.
For large depositors, the biggest practical improvement is better visibility into the rates banks are offering.
For banks, the change provides more room to price qualifying bulk deposits according to liquidity characteristics.
For ordinary savers, the direct impact is smaller, because a conventional retail FD below the bulk threshold remains governed by the applicable retail deposit-rate framework.
For borrowers, the most important issue is different: floating-rate EMIs are influenced by the benchmark attached to the loan. The October bulk-FD amendment should therefore not be presented as a direct EMI-reset rule.
At the same time, the broader monetary-policy environment deserves attention. The repo rate was 5.25% after the August 2026 policy meeting, while the RBI’s October MPC meeting is taking place from October 5 to 7. The decision due on October 7 could influence expectations for both lending and deposit rates, although the effect on individual products will depend on banks’ pricing and contractual benchmarks.
This is why savers and borrowers should look at the complete picture rather than reacting to one headline.
Conclusion: RBI’s New Bulk FD Rules Make Rate Comparison More Important
The RBI bulk FD rules effective from October 1, 2026 represent a meaningful change in how banks disclose and price large deposits.
Banks now have to publish bulk-deposit interest rates on their websites each business day by 10:00 a.m., with a 10-minute grace period. At the same time, eligible bulk deposits can be priced differently based on applicable liquidity run-off characteristics under the LCR framework.
For large depositors, this means greater visibility into the rates being offered and a stronger basis for comparing products.
But the new framework does not mean that every FD rate will rise, nor does it directly change home-loan EMIs.
The relationship between FD rates, bank funding costs, loan rates and EMIs is more nuanced. Floating-rate loans are linked to their applicable benchmarks and reset mechanisms, while deposit rates are influenced by each bank’s funding needs, liquidity position, competition and broader interest-rate conditions.
For investors, the practical lesson is simple: do not chase an FD rate without checking the complete product.
Before investing a large amount, compare the published rate, tenure, liquidity conditions, premature-withdrawal rules, tax implications and concentration risk. If you have a floating-rate loan, check your benchmark and reset date instead of assuming that every RBI banking change will immediately alter your EMI.
The October 2026 RBI changes make transparency more important than ever. Use the newly available rate information to compare banks carefully, review your existing deposits and loans, and make financial decisions based on your own cash-flow needs rather than headlines.
Before booking or renewing a large FD, check the latest rate published by your bank, compare equivalent products across institutions, and review the RBI’s latest monetary-policy decision and your loan’s benchmark/reset terms.
Mutual Fund Myths 2026: SIP vs FD – Truths They Don’t Tell You
Share this content:
Post Comment